Trusted Licensed Moneylender in Singapore: 7 Critical Secrets to Borrow Safely, Legally, and Transparently
Navigating short-term liquidity deficits, sudden medical emergencies, home renovation shortfalls, or unexpected personal financial obligations requires access to secure credit solutions. Engaging a trusted licensed moneylender in Singapore provides residents, Singapore citizens, permanent residents, and foreign employment pass holders with a strictly regulated, transparent borrowing avenue governed by the Ministry of Law and the Registry of Moneylenders. In an era where sophisticated online loan scams and unlicensed loan sharks impersonate legal credit entities through encrypted messaging applications, understanding the rigorous legal framework established by the Moneylenders Act protects borrowers from predatory practices. Legitimate credit providers uphold statutory caps on interest rates, enforce standardized loan documentation, conduct face-to-face identity verifications, and submit credit histories to the Moneylenders Credit Bureau, ensuring borrowers secure fair financial relief without compromising their personal or financial security.
The Regulatory Framework: How the Ministry of Law Governs Legal Lending
Singapore maintains one of the most stringent and transparent consumer credit regulatory regimes in the world. The Moneylenders Act and Moneylenders Rules establish mandatory operating guidelines that all licensed lending entities must comply with to maintain active business registration.
Statutory Interest Rate Ceilings and Fee Restrictions
To eliminate usurious lending practices, the Ministry of Law imposes strict, legally binding maximum caps on interest rates, late fees, and administrative charges that any legal lender can levy:
- Maximum Monthly Interest Rate: Regardless of a borrower’s monthly income or collateral status, the statutory nominal interest rate cannot exceed 4.0% per month on the outstanding principal balance.
- Maximum Monthly Late Interest Rate: If a borrower defaults on a repayment installment, late interest is strictly capped at 4.0% per month, calculated solely on the overdue repayment amount, not on the total outstanding loan principal.
- Administrative Upfront Fee Limit: Lenders may charge a one-time administrative fee upon loan grant, but this fee cannot exceed 10.0% of the principal loan amount.
- Late Repayment Fee Cap: Late payment fees cannot exceed a statutory maximum of $60 SGD per month of delayed payment.
- Total Permitted Borrowing Cost Ceiling: The cumulative total of all charges—including interest, late interest, administrative fees, and late payment penalties—cannot exceed 100% of the initial principal loan sum.
Mandatory Registry of Moneylenders Listing
The Registry of Moneylenders, operating under the Insolvency and Public Trustee’s Office, maintains an official, publicly accessible list of all authorized credit providers in the country. This registry is updated on a monthly basis, detailing business names, corporate registration numbers, official office telephone lines, and verified physical addresses. Any entity extending loan offers that does not appear on this official government registry operates illegally.
Strict Advertising Regulations and the Elimination of Cold-Contact Solicitation
Under Singapore law, legitimate licensed lenders face severe marketing restrictions designed to prevent aggressive debt solicitation. A legal lender is strictly prohibited from sending unsolicited SMS text messages, making cold telephone calls, or marketing via WhatsApp, Telegram, or social media direct messages. Legitimate credit providers may only advertise through:
- Their official, registered corporate website.
- Business or consumer phone directories approved by the Registry.
- Clear signage positioned directly within or on the exterior facade of their approved physical office premises.
Identifying Unlicensed Lenders vs. Licensed Credit Providers
Distinguishing between a legitimate credit provider and an illegal loan shark is straightforward when evaluating adherence to statutory operating procedures.
Physical Office Presence and Mandatory Face-to-Face Verification
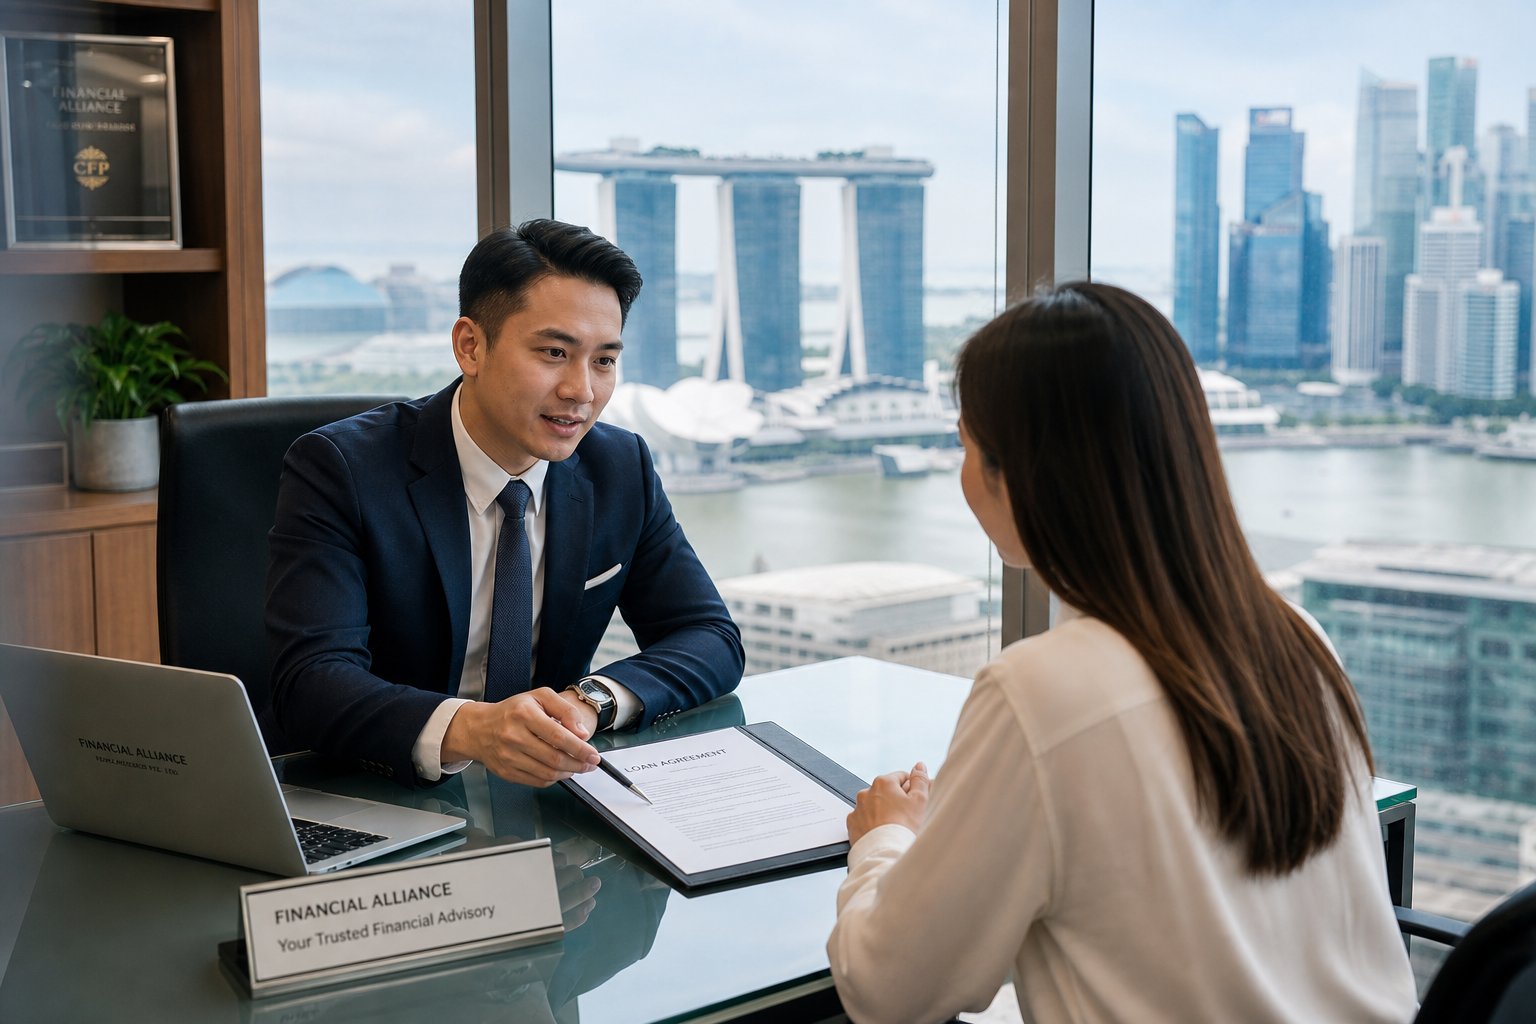
The most critical legal safeguard is mandatory in-person identity verification. By law, a loan contract cannot be executed, finalized, or disbursed remotely via phone or online messaging. Borrowers are required to visit the lender’s approved physical office premises to present physical National Registration Identity Cards or original passports, review terms, and sign physical documentation in the presence of a loan officer.
Remote Transfer and Advance Fee Scams
Illegal loan operators frequently promise instant online approval with zero documentation, demanding that borrowers transfer a processing fee, collateral deposit, or government tax clearance fee via PayNow before funds are released. A trusted licensed moneylender in Singapore will never ask for upfront payment transfers before loan disbursement; all legal administrative fees are subtracted directly from the disbursed principal sum at the time of contract execution.
Transparency in Contract Terms and Note of Contract Requirements
Before handing over funds, a registered credit officer must provide a formal Note of Contract written in a language the borrower fully understands. The officer is legally mandated to explain every clause, including the exact repayment schedule, monthly interest rate, late fees, and accepted repayment modes, ensuring complete transparency before obtaining the borrower’s signature.
Comparative Distinction: Legal Moneylenders vs. Illegal Loan Sharks
| Operational Dimension | Trusted Licensed Moneylender | Unlicensed Operator / Loan Shark |
|---|---|---|
| Regulatory Authority | Governed by Ministry of Law & Registry | Unregulated, illegal criminal operation |
| Monthly Interest Rate | Strictly capped at a maximum of 4.0% per month | Arbitrary rates (frequently 20% to 50% weekly) |
| Solicitations & Marketing | Strictly limited to official website and directory | Spam SMS, Telegram, WhatsApp, unsolicited calls |
| Identity & Contract Signing | Mandatory in-person verification at licensed office | Remote promises, no physical office, zero contracts |
| Upfront Fees | Up to 10% deducted from principal at disbursement | Demands advance cash/PayNow transfers before release |
| Data Privacy & Bureau Reporting | Reports securely to Moneylenders Credit Bureau | Uses personal data for harassment, threats, and doxxing |
Loan Structures and Maximum Borrowing Limits in Singapore
Singapore law protects consumers from excessive debt accumulation by establishing clear borrowing limits tied directly to individual annual income tiers.
Statutory Borrowing Limits for Singapore Citizens and Permanent Residents
- Annual income below $20,000 SGD: Borrowers may obtain an aggregate maximum of up to $3,000 SGD across all registered lenders in Singapore.
- Annual income of $20,000 SGD or more: Borrowers may access loans up to six times their verified monthly income across all licensed lenders combined.
Statutory Borrowing Limits for Foreigners Residing in Singapore
Foreign nationals holding valid Employment Passes, S Passes, or Work Permits are also protected under statutory tiers:
- Annual income below $10,000 SGD: Aggregate borrowing limit capped at $500 SGD.
- Annual income between $10,000 SGD and $20,000 SGD: Aggregate borrowing limit capped at $3,000 SGD.
- Annual income of $20,000 SGD or higher: Aggregate borrowing limit capped at six times verified monthly income.
Common Financing Solutions Provided by Legal Lenders
- Personal Loans: Unsecured credit designed for unexpected personal emergencies, medical expenses, or sudden travel needs.
- Business Working Capital Loans: Short-term bridge financing tailored for sole proprietors and small enterprises awaiting client accounts receivable.
- Debt Consolidation Financing: Restructuring multiple high-interest retail debts into a single, structured monthly installment schedule to regain financial control.
- Payday Bridge Loans: Short-duration advances intended to cover critical living expenses until the next scheduled salary crediting date.
The Role of the Moneylenders Credit Bureau
When applying for credit with a legal lending institution, the lender pulls a comprehensive credit report from the Moneylenders Credit Bureau.
Tracking Credit Exposure and Repayment History
The bureau maintains a centralized repository of all loan accounts, approved credit limits, outstanding balances, and historical repayment records across every licensed lender in the country. This system prevents borrowers from taking on unsustainable debt across multiple firms while enabling disciplined borrowers to build positive credit ratings.
Preserving Credit Health Through Timely Repayment
Consistently making scheduled loan repayments on or before the due date creates a positive credit profile within the bureau’s database. Demonstrating repayment reliability enables borrowers to negotiate higher credit approvals, faster processing, and flexible repayment terms on future credit facilities.
Essential Documentation Required for Legal Loan Processing
To expedite the application and ensure smooth verification during an in-person office consultation, borrowers should prepare the following standard documents:
- Identification: Original physical National Registration Identity Card for citizens and permanent residents; valid Passport and original Employment Pass for foreign workers.
- Proof of Income: Latest three months of computer-generated payslips or recent electronic CPF Contribution History Statements.
- Income Tax Assessment: Latest Notice of Assessment accessed via SingPass.
- Proof of Residence: Recent utility bills, telecom statements, or signed residential tenancy agreements verifying a current residential address.
Frequently Asked Questions About a Trusted Licensed Moneylender in Singapore
How can I verify that a moneylender in Singapore is legally licensed?
Check the official Registry of Moneylenders list published on the Ministry of Law website to confirm that the business name, license number, and office address match exactly.
What is the maximum legal interest rate a licensed moneylender can charge in Singapore?
Under Ministry of Law regulations, the maximum interest rate a licensed moneylender can charge is strictly capped at 4.0% per month on the outstanding principal balance.
Can a licensed moneylender approve and disburse a loan completely online without an office visit?
No, Singapore law strictly requires borrowers to complete in-person identity verification and contract signing at the lender’s approved physical office premises before funds can be disbursed.
What should I do if I receive a loan offer via WhatsApp or SMS?
Ignore and block the sender immediately, as legitimate licensed moneylenders are strictly prohibited from advertising or soliciting loans via WhatsApp, Telegram, or unsolicited SMS messages.
How much can I borrow based on my annual salary in Singapore?
If you earn $20,000 SGD or more annually, you can borrow up to six times your monthly income across all licensed lenders; if you earn under $20,000 SGD, the aggregate cap is $3,000 SGD.
Can taking a loan from a licensed moneylender affect my bank credit score?
Lenders report data to the Moneylenders Credit Bureau, which is separate from the Credit Bureau Singapore used by major commercial banks; however, maintaining punctual repayments ensures overall financial standing remains strong.
Conclusion
Securing responsible, transparent credit during times of financial need requires diligence, clear understanding of lending laws, and verification of institutional credentials. Selecting a trusted licensed moneylender in Singapore ensures that your borrowing experience is protected by strict Ministry of Law oversight, statutory interest rate caps, and transparent contract terms. By verifying active licensure on the official Registry of Moneylenders, avoiding unsolicited remote messaging scams, and carefully budgeting monthly repayments within your financial means, you can resolve short-term financial demands safely and effectively. Working with reputable financial providers guarantees legal protection, preserves personal privacy, and provides a clear, manageable path toward financial stability.